

𝘊𝘢𝘭𝘭 𝘮𝘦 𝘐𝘴𝘩𝘮𝘢𝘦𝘭. 𝘚𝘰𝘮𝘦 𝘺𝘦𝘢𝘳𝘴 𝘢𝘨𝘰 - 𝘯𝘦𝘷𝘦𝘳 𝘮𝘪𝘯𝘥 𝘩𝘰𝘸 𝘭𝘰𝘯𝘨 𝘱𝘳𝘦𝘤𝘪𝘴𝘦𝘭𝘺 - 𝘩𝘢𝘷𝘪𝘯𝘨 𝘭𝘪𝘵𝘵𝘭𝘦 𝘰𝘳 𝘯𝘰 𝘮𝘰𝘯𝘦𝘺 𝘪𝘯 𝘮𝘺 𝘱𝘶𝘳𝘴𝘦, 𝘢𝘯𝘥 𝘯𝘰𝘵𝘩𝘪𝘯𝘨 𝘱𝘢𝘳𝘵𝘪𝘤𝘶𝘭𝘢𝘳 𝘵𝘰 𝘪𝘯𝘵𝘦𝘳𝘦𝘴𝘵 𝘮𝘦 𝘢𝘴𝘪𝘥𝘦 𝘧𝘳𝘰𝘮 𝘢𝘯𝘵𝘪𝘵𝘳𝘶𝘴𝘵, 𝘐 𝘵𝘩𝘰𝘶𝘨𝘩𝘵 𝘐 𝘸𝘰𝘶𝘭𝘥 𝘴𝘢𝘪𝘭 𝘢𝘣𝘰𝘶𝘵 𝘢 𝘭𝘪𝘵𝘵𝘭𝘦 𝘢𝘯𝘥 𝘴𝘦𝘦 𝘵𝘩𝘦 𝘰𝘶𝘵𝘱𝘢𝘵𝘪𝘦𝘯𝘵 𝘱𝘳𝘰𝘷𝘪𝘥𝘦𝘳 𝘱𝘢𝘳𝘵 𝘰𝘧 𝘵𝘩𝘦 𝘸𝘰𝘳𝘭𝘥.
Epic owns the enterprise. Its acute-care share climbed to 43.7% in 2025, up from 42.3% a year prior, and it keeps winning the few large decisions left. Their architectural approach of a single integrated monolith underpins their dominance in the enterprise: every department writing to one shared database, each new user compounding the value for everyone already on it.
But they have not won all markets. From There Will Be Bundling, we saw how system of record markets (and the EHR market) are typically fractal: concentrated at the top around two or three integrated systems of record, then fragmenting into hundreds of niche players as you move downmarket and workflow needs get more specific.
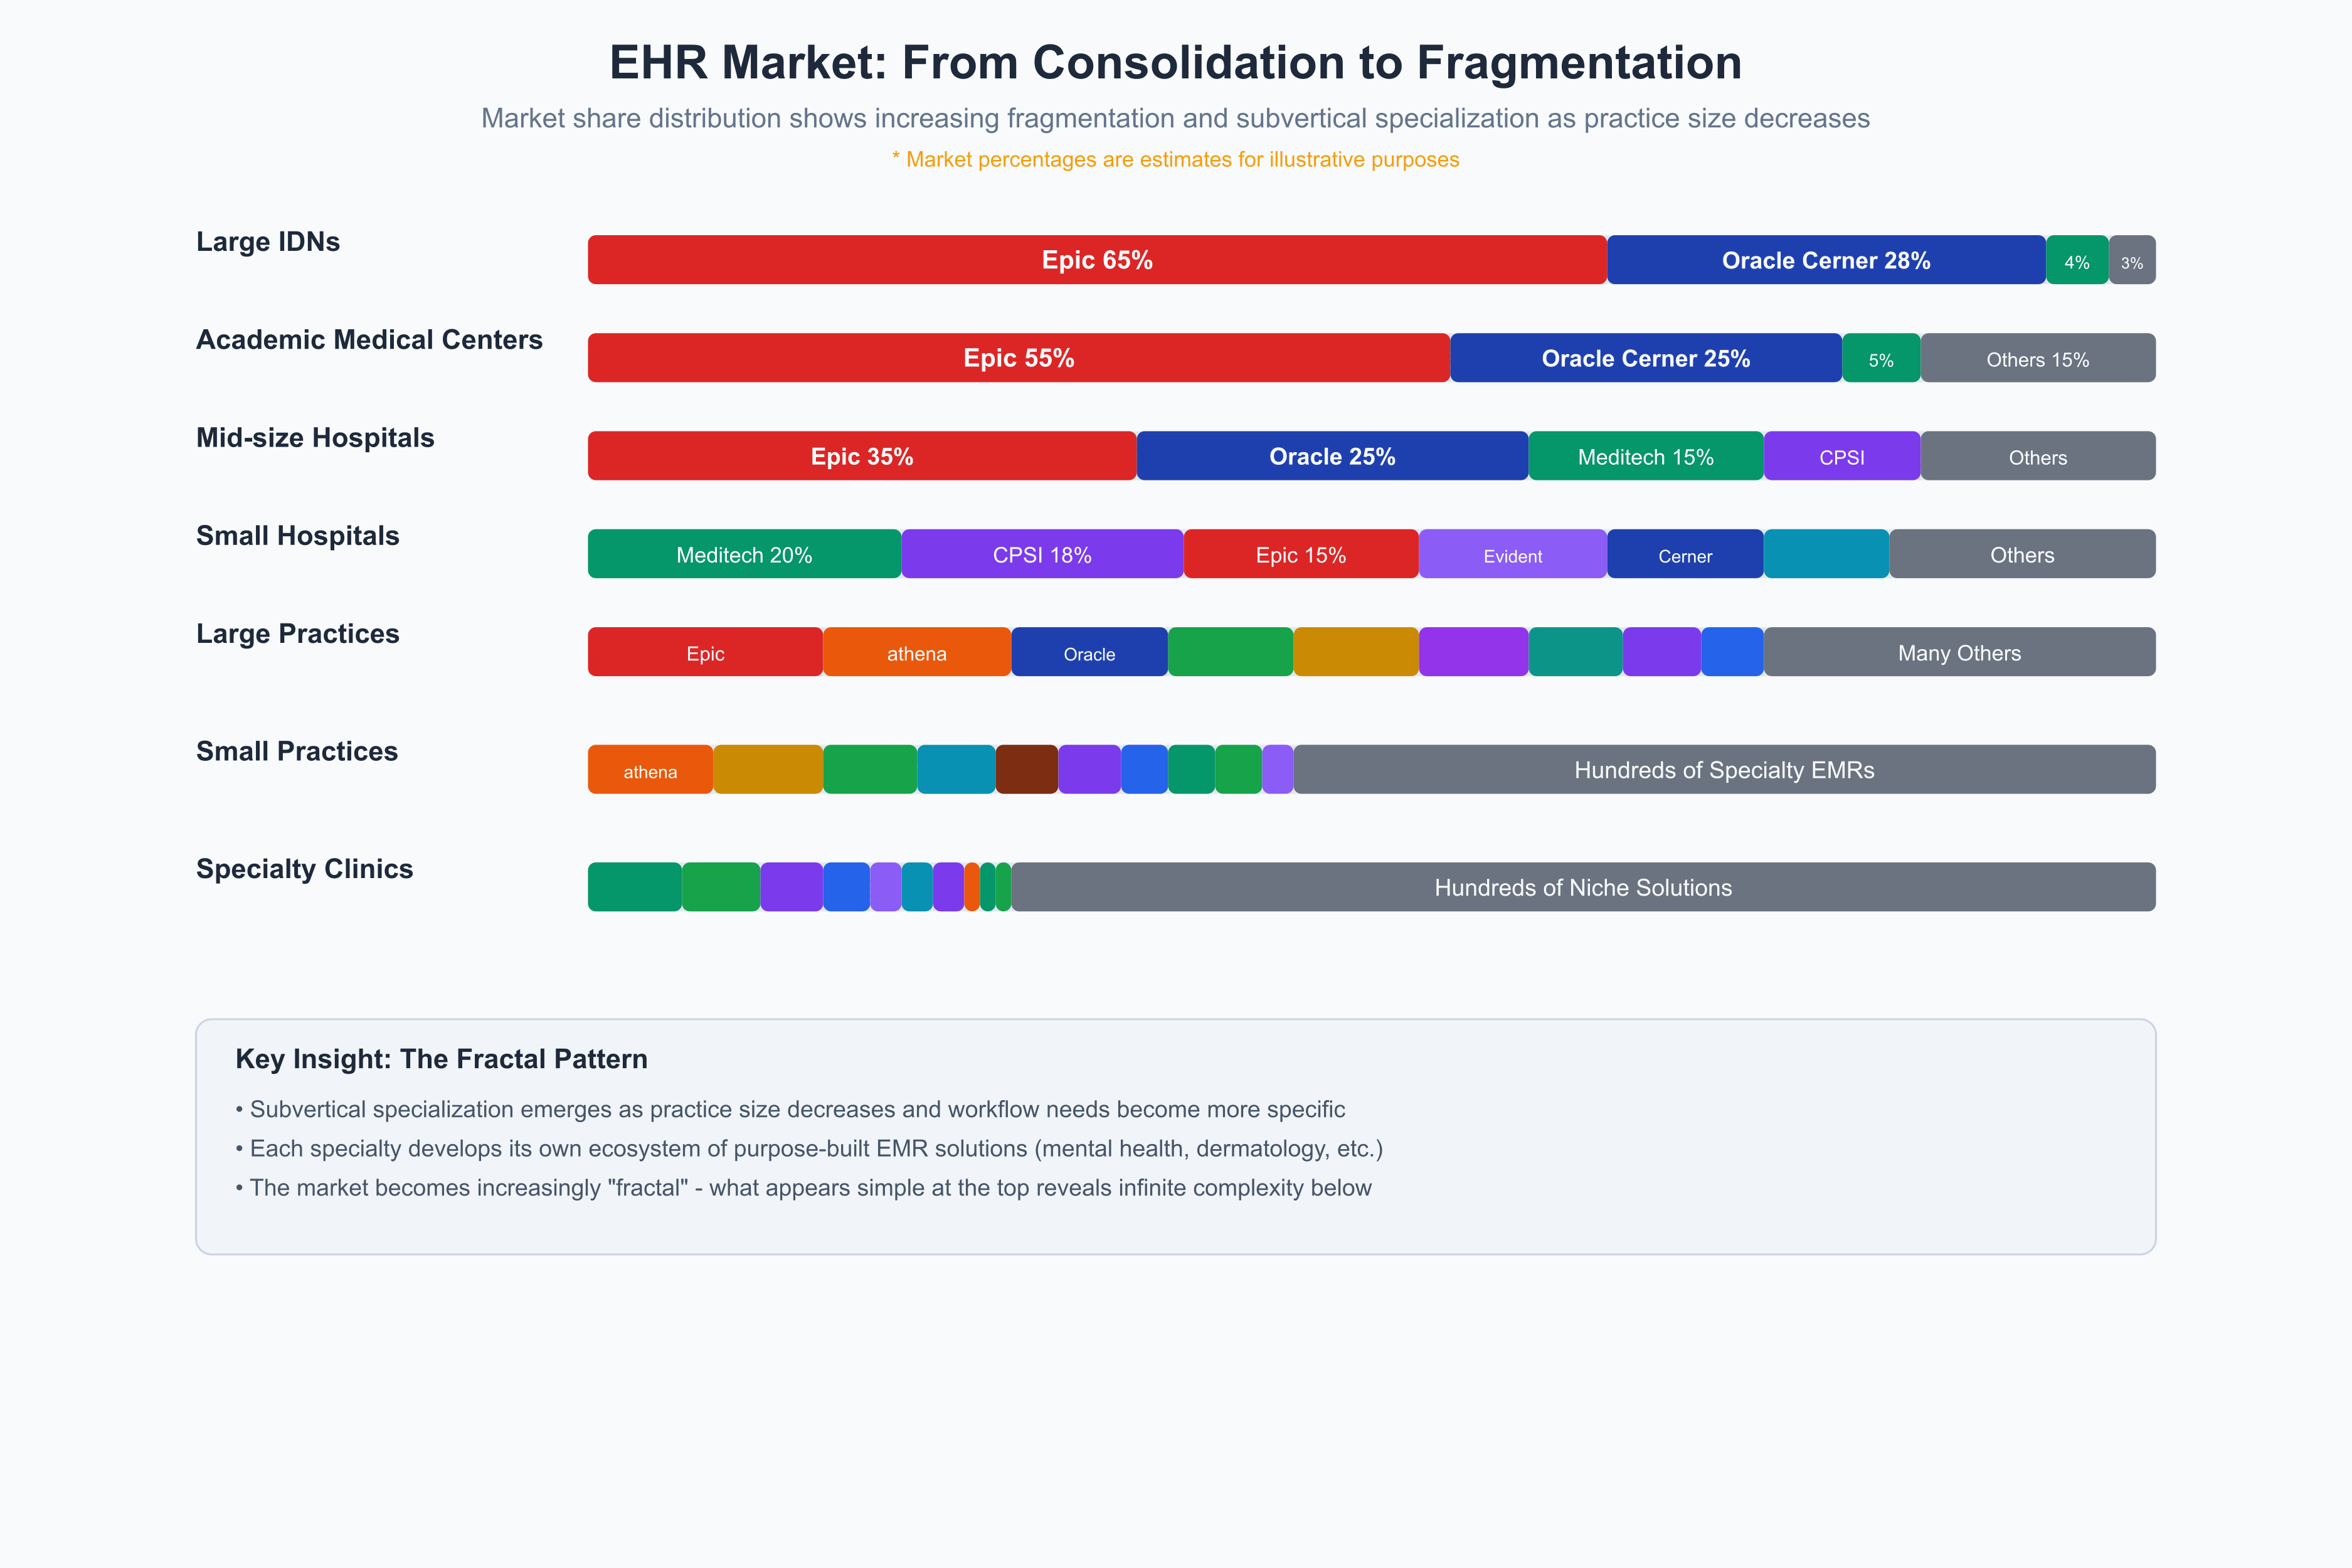
The long tail of solo practices or 5-provider groups has long been their white whale for a few reasons:
Epic's long, heavy implementations don’t match small practice staffing or expectations.
The EHR’s premium cost structure often prices these practices out entirely.
Most importantly, the main differentiator (a monolithic mega-database and associated intra-organizational network effects) that sell the enterprise need many departments and roles to matter. A solo practice has neither!
That segment belongs to athenahealth, eClinicalWorks, PracticeFusion, and a field of niche speciality specific SaaS. And so we see them chase it like health tech’s Captain Ahab:
Community Connect (2007) lets a small org ride a host system's instance. It’s been incredibly successful in aligning multiparty incentives: the host pulls affiliated practices onto its instance, deepening referral capture and earning a hosting stipend; the small practice gets Epic without the full price tag or implementation lift, plus clean data exchange with the partners it already leans on; and Epic books share in a segment it can't profitably serve itself. But there’s a ceiling in that practice autonomy is sacrificed. Truly independent groups wanting no master have nowhere to go.
Epic Hosting (2015) runs the same full Epic, with the data center handed back to Epic. You still buy, license, and build your own instance, while Epic just operates the infrastructure in its own Verona and Rochester facilities. It removes the servers and the ops staff, not the cost or the implementation. Fittingly, it's a re-entry: Epic started in 1979 as a time-sharing firm, so vendor-operated computing is where the company began. The result: 162 health-system tenants on an
epichosted.comendpoints (30% of all branded Epic endpoints), with Johns Hopkins, Memorial Sloan Kettering, CommonSpirit, and Advocate Aurora on the list. It helps a customer big enough to own a full Epic, but doesn’t change the equation for a practice that can't.Sonnet (2018) was the slimmed-down build for small hospitals and physician groups. The logic was that Epic's implementation pain came from sheer surface area, so stripping modules down to a core feature set would shorten timelines and lower the price enough to compete with athenahealth and eClinicalWorks on their own turf. It never caught on. The orgs that wanted Epic wanted the whole thing, and the orgs that wanted lean and cheap had better-fit options already. After years of muted uptake, Sonnet was effectively shelved.
Which brings us to Garden Plot (2022), essentially Community Connect with Epic itself as the host. As a shared, cloud-hosted Epic tenant with third parties like Availity and Surescripts pre-wired, the idea has been that a small practice can land on Epic without forfeiting its neutrality. In a multi-hospital market, riding one system’s Community Connect instance reads as picking a side and often serves as a simple precursor to acquisition.
From our exploration of the Garden Plot SMS page last summer, there were around 24 total organizations listed. Since then, that number has hardly budged, increasing to 28. Moreover, the last time the page was updated was nearly 9 months ago (on September 9, 2025). However, it could be that the SMS page is a weak proxy for the total count. If it only captures practices that opted into Epic’s stock texting program, it could undercount the real number.
